Author: Anita

  • Knight Eady: Using Low Cost Tools to Create a High Value Workspace

    Knight Eady: Using Low Cost Tools to Create a High Value Workspace

    Knight Eady is a Birmingham-based sports marketing and event management company.  Over their three years of existence, Knight Eady has grown from the initial two founders to a team of more than 20 employees.  And “Team” is the right word.  If you watch Knight Eady’s employees interact, it feels like you are watching a sports team in the locker room before the game – minus the “locker room talk”.  They are fun, passionate and focused and this culture is no accident.

    One of Knight Eady’s core values is to create an engaging and contagious work environment.  Their interpretation of this is that they are all family and that the workplace needs to be a joyful and inviting place and their office space is designed to help them accomplish this goal.  However, because the founders hoped and believed that their company would outgrow their space relatively quickly, they were careful to stick to a limited budget when designing their space to their needs.

    Knight Eady’s current space features 20 foot high ceilings with full height windows along one wall.  To maximize this natural light, the company utilized a primarily open floor plan, with the only enclosed spaces being two private offices, a conference room and a huddle room.

    Because the space is open plan, the company added some small phone booth spaces for privacy and noise control. In order to make best use of the ceiling height in the space, they built a mezzanine level on top of the phone booths where two employees sit in a virtual sky box.


    The company’s love for sports is reflected throughout their space.  One wall is decorated with leaves and a brick overlay to resemble the back wall at Wrigley field, complete with yardage markers on the barn door that slides open to reveal the huddle room.  In their conference room, one entire wall features a photo of the sellout crowd at one of their recent events, the Rocket City Classic.


    Both in their original 1,580 square foot space at Birmingham’s tech incubator, Innovation Depot, as well as the new 3,200 square foot Depot space to which they recently relocated, Knight Eady placed bold typographic statements on the walls in their brand’s signature turquoise color.  

    The floors of Knight Eady’s new space were originally covered in gray carpet tile.  While Knight Eady considered removing the carpet in favor of the underlying concrete, potential acoustic problems with that approach prompted them to instead replace some of the tiles with turquoise carpet tiles for a look reflective of their brand.

    Knight Eady utilizes benching in their space rather than high walled cubicles.  It keeps the space open and interaction easy.  Further reflective of their family feel, they had a large custom farmhouse table built for the center of the space.  They can seat everyone around the table for a meal. 

    As a real estate broker who loves working with dynamic young companies, I think Knight Eady did a remarkable job of using low cost tools such as color, theme and the open space culture to create the energy and feel they wanted in their workspace.

  • What Five Interior Finishes Make a Class A Office Build Out Class A?

    What Five Interior Finishes Make a Class A Office Build Out Class A?

    If you are looking at building out new offices for your firm or company in a new or existing class A building, landlords may try to lure you to their buildings with offers of a “turnkey” buildout.  By definition, this means that the landlord will complete the buildout of your desired floorplan for you at its cost.  Usually the landlord will do so with “building standard” finishes which typically include a standard type and grade of carpet, standard baseboards, lighting, etc.

    Because landlords are cost conscious and interested in ensuring that they negotiate a good deal for themselves, their building standards may not be reflective of the class A level of finish you envision.

    I spoke with several well-respected architects to get their opinions on what finishes should be contemplated to ensure that your space has a Class A look and feel.  The following are the five finishes these architects identified.

    Doors

    Tall doors make offices look more refined and professional.  In addition, solid doors hold up well to commercial use.  Lissy Frese with Cohen Carnaggio Reynolds recommends her clients utilize doors that are a minimum 8’ high and 1 ¾” thick with full height doors preferred.

    Ceilings

    To ensure a feeling of openness and a better distribution of natural light within space, Jill Hicks of Jill Hicks Design suggests that finished ceiling heights should be at least 9’ and preferably 10’, especially in today’s era of open floor plan.   If you are considering an existing building where the ceiling heights are somewhat lower, Frese recommends you consider an open ceiling as that will increase the open height above work areas.

    Donna Dowling of KPS Group emphasizes that ceiling grids should be 2’ by 2’ with tegular tiles (a tile that has an edge detail that allows a suspended ceiling panel to extend below the grid, making the grid less noticeable).  Even if you are moving into an existing building with 2’ by 4’ tiles, the grid can be easily upgraded to a 2’ by 2’ layout.

    Carpet

    While traditional rolled carpet is less expensive than carpet tiles, carpet tiles allow the user to easily replace carpet in areas of greater wear without replacing all of the carpet.  Tiles are becoming the industry standard and all of the architects urge their clients to choose them and to order extra tiles for future replacements.

    Lighting

    New Class A spaces are usually lit with LED lights that feature both direct and indirect lighting which reflects light both upward and downward.  This provides both a soft and even illumination and an extra punch of light on the work plane.  Studies by Cornell University have shown that the occupants of office spaces prefer to work under indirect and direct/indirect lighting and that there is a direct correlation between worker productivity and good lighting.

    Sound Insulation

    Because this is something that you do not see, this finish is often overlooked until a tenant has moved into its new space and the employees realize they can hear every word of their co-worker’s conversation in the office next door.  Sound insulation can be optimized easily when considered at the design stage.  The architects interviewed for this article collectively suggest that offices be built with 3 5/8” metal studs in the walls, the walls extend at least 6” above the ceiling grid and insulation be laid on top of the wall to 2’ on either side it.

    If you are anticipating a Class A environment, it is important to ensure that at a minimum these features are included in the build out the landlord is providing.  It is important to address these up front, before the deal is completed, and certainly before the space is built out.  The longer this discussion is put off the more expensive the cost to correct.

  • What Will a Trump Presidency Mean to Real Estate Tax Reform?

    What Will a Trump Presidency Mean to Real Estate Tax Reform?

    Guest Blogger: John D. Pickering, Partner at Balch & Bingham, LLP

    Predicting the future for commercial real estate is always difficult, but it’s made significantly more so this year because of the real possibility of massive federal income tax reform.  Big-time reform would have been unlikely if Hillary Clinton had won the White House and divided government had continued, but with a Trump victory and Republican control of both houses on Capitol Hill, tax reform on a 1986 scale may really happen.  That “1986” reference should grab the attention of anyone working in commercial real estate – older readers will remember the impact on the industry of the 1986 reform, and younger readers studied it in school or have heard the stories from their more senior colleagues.

    So could it happen again?  Maybe.  Some of the specific changes being considered would certainly have big impacts on our industry.  For example, the elimination of 1031 tax-free exchanges, removing the deductibility of interest on real estate loans, and ending the current favorable treatment for carried interest.  If the industry is hit by all these changes at once, the consequences could be especially painful.

    Let’s consider the context for these proposals.  Republicans are concerned about labor force size due to Baby Boomer retirements, a declining workforce participation and declining worker productivity.  The latter is a consequence in part of historically low levels of capital investment.  They hope to address these issues with large-scale reform that would include the following:

    –Corporate income tax rate cut (from 35% to 20% or lower)

    –Individual income tax rate cuts and simplification (three brackets instead of seven, with a top rate of 33%; increases in standard deductions to reduce need for itemization by many taxpayers)

    –Elimination of corporate and individual alternative minimum tax

    –Increases in child and dependent tax credits

    –Protection of interest rate deductibility for home acquisition financing, but elimination of deductibility of interest on all other types of loans, including home equity loans and commercial real estate loans

    –Elimination of estate tax

    –Creation of a special 25% rate for income from sole proprietorships and pass-through entities such as partnerships and LLCs, with reasonable salaries to owners being taxed at ordinary individual rates

    –Reorganization of the IRS into separate units for business and individual taxation, and the addition of a “small claims court” unit

    –Get rid of multi-year depreciation for business investment, so capital investments are fully expensed in the year they are made

    While these proposals are grounded in economic ideas about fair allocation of the tax burden and promoting economic growth, each industry will ask “what’s in it for me?”  For commercial real estate, the unfavorable proposals outlined above, or at least the ending of interest deductions, might be offset by the current year expensing of all capital investment expenditures, with the exception of land.  This proposal takes some getting used to for anyone who has thought in terms of 39-year depreciation!

    Watch what happens in Congress carefully this year.  It may have a significant impact on your livelihood.

  • New Open Offices Result in Increased Employee Attendance

    New Open Offices Result in Increased Employee Attendance

    Littler measures improvement one badge swipe at a time

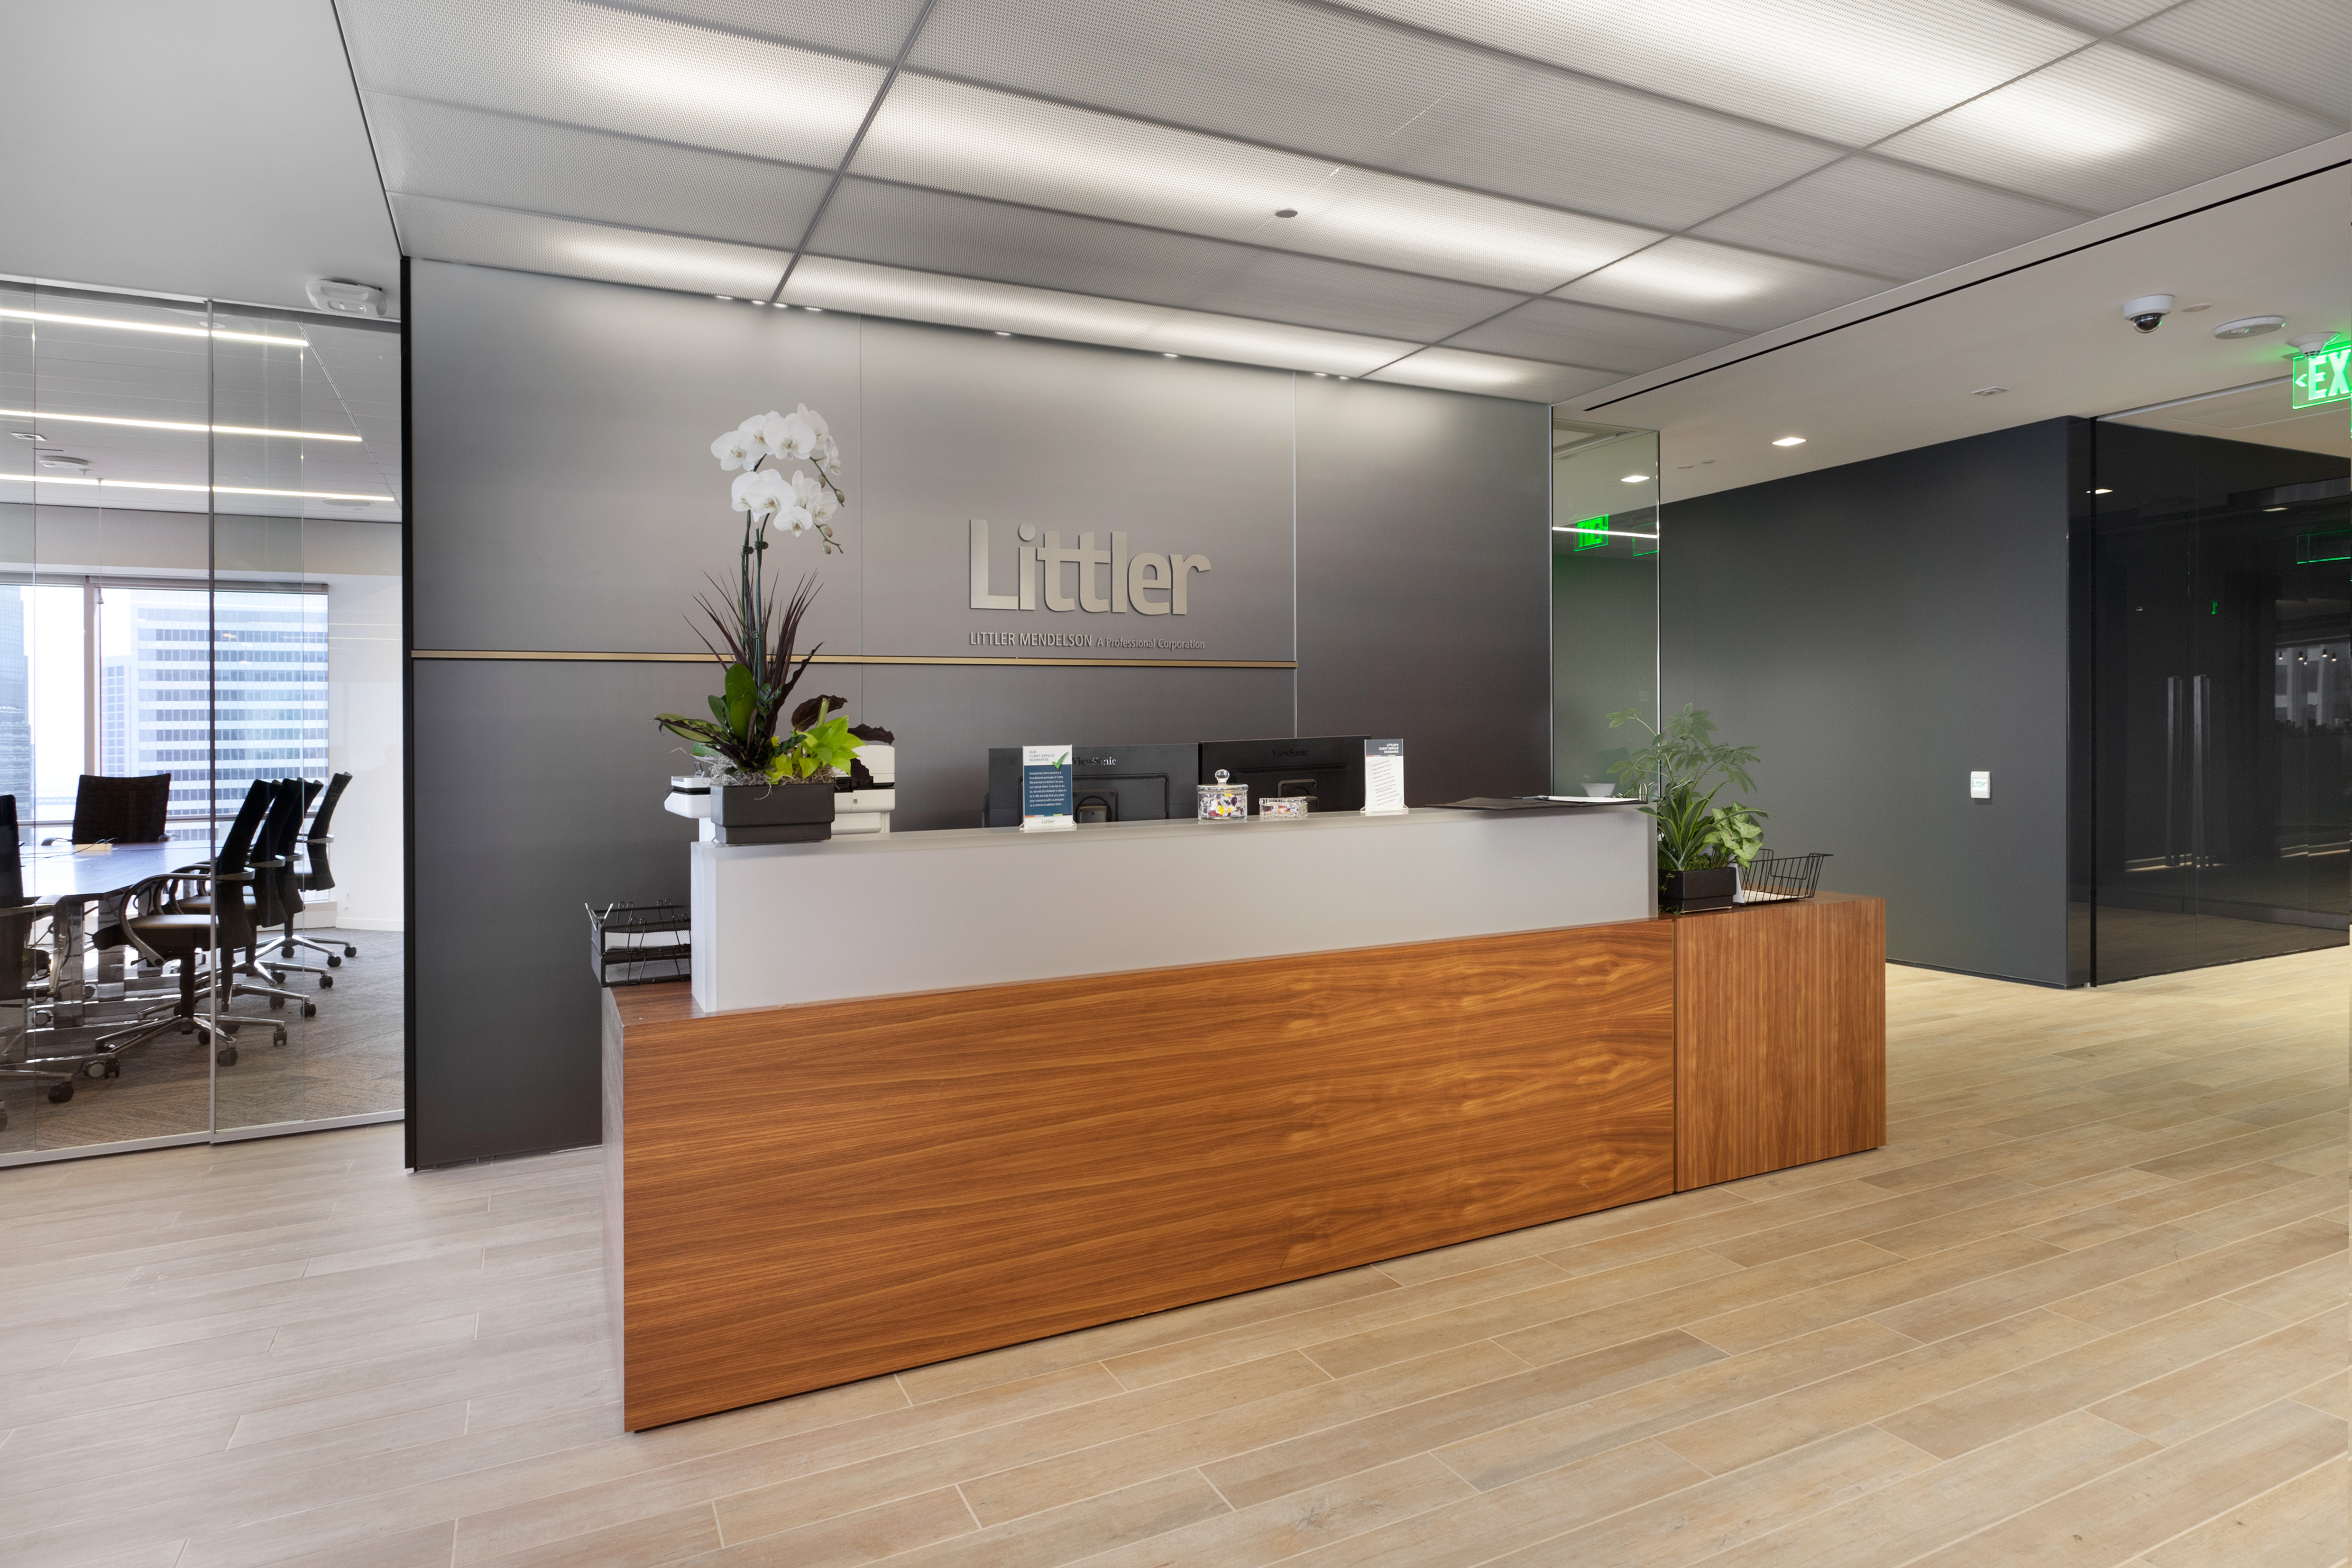
    Last year, after more than forty years at 650 California Street, law firm Littler Mendelson moved their San Francisco offices to 333 Bush Street.  The new design included standard sized offices of ~120 square feet with glass walls and low-height cubicles to maximize sight lines and interaction.  These open and airy new offices were built to maximize natural light and promote collaboration and interaction.

    Before and after the offices were built, Littler’s administration tracked how many days per week each San Francisco employee badged in and out of the office.  For instance, if an employee worked Monday through Friday every week, their attendance was 100%.  If they worked Saturdays as well, attendance was 120%.  This information was not tracked to spy on individual employees but rather to determine whether office attendance increased with the new build-out and if so, whether the increase was consistent across all roles – data entry clerks, accounting professionals, associates, partners, etc.

    What did they learn? Attendance across all roles increased in the new leaner but brighter space.  Essentially their employees voted in favor of the new space with their increased desire to be in the office.  Littler can now use this data to help sell the firm’s new space standards across their portfolio.

    Since increased office attendance was a goal with their new office space, this metric was the perfect measure.  What metrics might you use to measure the effectiveness of your space?  It depends on your goals but, like Littler, you may already have access to the data you need to track.

    To read about the novel way Littler assigned individual offices within this new space, click here.

  • Four Real Estate Benchmarks You Should Track and Why

    Four Real Estate Benchmarks You Should Track and Why

    If you are a business owner, services firm manager or corporate real estate director, you likely have some strategy regarding your real estate.  That strategy could be to contain costs, or to encourage interaction and collaboration between employees, or to ensure that you have sufficient flexibility to grow, shrink or relocate as your business requires.  In order to assess whether your strategy is working (and get buy in from the executive team), you need to determine which metrics measure strategic success and then start benchmarking those metrics over time internally and against your industry. 

    Which Metrics Should You Use?

    There are a number of them that we recommend, including:

    Square feet per employee:

    To determine this number, divide the total square footage your company owns or leases and actually OCCUPIES (exclude subleased space) by the total number of employees.  A simple lease tracking system can provide you the square footage numbers.  In the absence of such a database, the accounting people who pay rent or the attorneys who negotiate the leases usually have this data.

    You can also determine this ratio for each separate location.  This data can be used in several ways.  Some of our service provider clients compare the overall portfolio ratio with each office’s individual ratio to identify those offices that are significantly above or below the average.  Those offices may provide opportunities to right-size the space and improve portfolio efficiency.

    Other clients use this number to compare themselves to their industry.  Industry benchmarks for square foot per employee can be found in the International Facility Management Association’s (IFMA) annual benchmarking report or can be obtained from your real estate services provider.  For instance, the IFMA average for insurance industry occupiers may be 200 square feet per employee.  If you are an insurance company and you average 300 square feet per employee, the reason for the difference may be worth investigating and incorporating in your strategy.  If your strategy then becomes densification, you can compare your square feet per employee at the end of next year to this year’s number to determine whether the strategic decisions you made improved this metric over the year.

    Real estate cost per employee:

    It is the total real estate cost per employee divided the total number of employees.  To make this number meaningful, you need to define real estate cost.  It can include rent, operating expenses, utilities and/or taxes across the whole portfolio. To be meaningful, the components included should be the same year over year.  The data can usually be obtained from the accounting department at your organization.

    The real estate cost per employee is a great way to evaluate the relative cost of different locations.  For example, a law firm leasing five thousand square feet in downtown Manhattan for ten lawyers may pay $50,000 per lawyer for space.  If that same firm leases fifty thousand square feet in Birmingham for 100 lawyers, the cost per lawyer is $10,000.  The square feet per lawyer (500) is the same in both offices.  However, an improvement in the density of the Manhattan offices will produce an exponentially greater reduction in costs than that same improvement in Birmingham.  The law firm can use this data to identify high value cost savings opportunities.

    Internal vacancy rates (how many unassigned seats do you have?):

    To calculate this number, you need a seat count for each office as well as a headcount.  The criteria for determining the number of seats should be defined. For example, it could be one seat per workstation or office.  Conference and huddle room seats should not be counted unless they are used primarily as regular workspaces.  IT can be helpful in determining seat count as they can usually tell you how many phone lines or handsets are deployed and how many of those have numbers/employees assigned to them.

    Once determined, this seat count can then be divided by the total number of employees to determine what percentage of your seats are vacant.  Depending on the volatility of a business and its growth plans, optimal vacancy rates may be as close to zero as possible or as high as 10-15% to allow for fast growth.

    If you have a badge security system, you can also determine how many employees on average are in the office on a daily basis.  This information can help you understand whether those assigned seats are actually being occupied by their assigned employee each day.  In industries like accounting this data has been used to justify a hoteling strategy where some of the seats are left unassigned and may be used by any employee in the office on a given day.

    Employee attendance, productivity and satisfaction:

    These measures are more subjective but they can help you identify strength and weaknesses in your workplace design and operation.  They can also be utilized to gauge whether a change made to improve design or operations was effective.  When Deloitte built out 500,000 square feet in a new, highly-amenitized building in Toronto, the number of employees going into the Toronto office to work (rather than working remotely) sky-rocketed.  Because this increase was a desirable to Deloitte, they used this data to help them refine their strategy for future locations to focus on amenities.

    Your real estate,whether a single location or a multi-market portfolio of properties and leases, is a significant asset and cost to your organization. It houses your employees, facilitates the operation of your business and brands your company to your clients. An evaluation of the metrics of your real estate can help you understand where you are and provide a benchmark for measuring future success.

  • Building Sale + Land Sale + Furniture Sale + New Office Lease = Wisconsin Fun With ProAssurance

    Building Sale + Land Sale + Furniture Sale + New Office Lease = Wisconsin Fun With ProAssurance

    I hope everyone shares this sentiment, certainly for me, 2016 was a fun year.  Professionally, with my partner, Joe, I was able to complete some interesting transactions that created a ton of value for our clients.  One of the highlights was a project I worked on with our client, ProAssurance, and its director of real estate, JC Blakely. 

    We have been working with ProAssurance for several years and as part of that strategic partnership, we monitor their real estate portfolio for opportunities to save them money and/or create value.  ProAssurance’s portfolio includes some owned buildings across the country acquired through a various mergers and acquisitions.  Recently, some of the operations previously handled out of one of these buildings, a 35,000 square foot office building in Madison Wisconsin, were consolidated to another location.  This meant that ProAssurance had an opportunity to sell the building and relocate to an appropriately-sized space in a building with more amenities.  The building came with a few acres of cropland adjacent to the building and ProAssurance had been leasing that cropland to a farmer.

    We partnered with a local Madison broker with whom we had worked previously — Mike Herl.  Because the land and the building were in a developing area of Madison, we thought there was a great opportunity to sell both the building and the land at a great price for ProAssurance.

    In order to ensure that there were no negative tax consequences associated with the sale of cropland due to its likely conversion to commercial development, we identified a qualified WI tax lawyer to advise on the process.  Once that hurtle was cleared, we placed the property on the market.

    Several buyers were quickly identified and two offers were received.  We negotiated on the best overall offer while also working to secure leased replacement space for ProAssurance.  Because the buyer wanted to close quickly, we negotiated a leaseback post-sale until ProAssurance’s new space could be built out. We were also able to negotiate the sale to the buyer of ProAssurance’s fully amortized furniture inventory.

    The building brought a purchase price of $4.7M and the cropland brought an additional $1.75M.

    The sale and relocation resulted in a 70% net reduction in ProAssurance’s occupied space in Madison and operating costs were reduced significantly.  In addition, in the new location, all employees will be located on the same floor in modern space built to increase collaboration.  Finally, ProAssurance will no longer have to provide facility management for a building remotely located and not fully occupied. Working on a team so focused on getting the best result for ProAssurance made all of the challenges associated with selling a building, structuring a lease back on a portion of the space and negotiating for a relocation site worthwhile.  It is rewarding to watch it all come together and I can’t wait for the next challenge in 2017!

    Photo credit: CommercialSearch.com 

  • 2016 Blog Year in Review

    2016 Blog Year in Review

    Ten years ago, I was contemplating changing employers after almost ten years at the same company.  I called my wise and fearless friend, Craig McKesson, for advice and he told me “if you’re not growing, you’re dying”.  Please know that my modus operandi up to this point was to take the safest route, so this advice was tough love.  Nonetheless, I made the change and I grew and it was fantastic.  Even better, I learned how much fun change can be.  So, earlier this year and in keeping with this philosophy, I started writing this blog.

    I have traveled coast to coast and covered a variety of subjects hopefully of interest to everyone from my fellow real estate brokers to law firm COOs to tech company founders.

    In the legal realm, I talked about whether law firms could benefit from having  advisory boards made up of non-lawyers.  My partner and I also surveyed in-house counsel at 32 large companies and shared what we learned from them about what they are looking for from outside counsel.

    I also get into law office design and space issues including Littler Mendelson’s new 120 square foot offices and their novel approach to determining who gets the good office.  Here’s a brilliant idea to create more space in an existing law office.  This post may help law firms plan their space to evolve with their business and this post can help them decidewhether or not associate opinions matter in the design of law firm space.  I toured a local example of a progressive law firm buildout and got some great ideas from a not-so-local firm, DLA Piper.  Finally, with some help from my partner, Joe, I examine whether a professional services firm should own its own building or the one next door.

    Start-up founders and those interested in progressive office space may want to read Parts 1, 2, 3, 4 and 5 of my series on San Francisco’s tech spaces.  For an East Coast rendition of this West Coast adventure, read this post about building for serendipity at Google NYC.  If you are trying to build a great company culture, read this post about fun employee perks.  If that culture might include a distributed workforce, read this post about local fast-burner, Fleetio.

    If you develop or redevelop real estate, please read this post about the importance of “place”  as learned from Brookfield Properties and this one about making the most of older buildings.

    If you manage a corporate real estate portfolio, please read this post about why you need renewal rights and then this article about the effect of the new FASB rules those rights.  For help preparing for the onslaught of operating expense reconciliations you will be receiving first quarter, read this post – Operating Expense Desk Audit 101.  If you are a property manager seeking to justify your existence, read this article about the importance of your role in the real estate eco system.

    If you own property, this blog post is a reminder about the importance of up-to-date CAD files.  And this, my most-read post (written by John Pickering), discusses whether employers or building owners can ban guns from the office.

    If you are a real estate lawyer or broker, you might want to read this post about whether a witness is required on your lease or this one which details whether an email can modify a real estate lease or sale contract.  This post give a quick overview of five areas often overlooked when closing a real estate sale.  If you are working on a lease for new construction, you might find some helpful hints here.

    I will leave you with two of my favorites:  this post about the value of surprises and this post about the importance of ending on a high note.  Thanks for 2016.  See you next year!

  • The Value of Surprises

    The Value of Surprises

    Surprises and vivid action matter far more than we imagine, and we regularly underinvest in them.  – Seth Godin

    I read this quote earlier this year and in reflecting on 2016, I am overwhelmed by its truth.  For me, the high points of the past year almost all embody at least one of these two characteristics.  As examples:

    ·         Receiving two small brass elephant bookends hand delivered to my house on the date of the SEC championship by friends who just knew that I would love them.  (Roll Tide!)

    ·         Reading a text from a vacationing client thanking me for my efforts on behalf of him and his company.  Incidentally, this is not the first time he has done something thoughtful like this.  And I would do anything for someone who treats me like such a valued partner.

    ·         Arriving to work to find a large bag of my favorite dark chocolate with a kind note from a co-worker who makes my life easier on a daily basis.

    ·         Enjoying a lovely dinner out with my husband compliments of my partner who appreciated my work on a deal.

    ·         Opening my mail to find an article that one of my blog readers thought I would find interesting.

    ·         Being awarded a Colliers Blue Mont Blanc pen in recognition of a career milestone at a staff meeting.

    ·         Having a friend who could give Martha Stewart competition come to my house at noon laden down with tableware to set a beautiful table for me for a party I had planned in the evening.

    The common thread?  When we are surprised, we recognize that someone was thinking of us and cared enough to let us know. And that feeling has staying power.  We may forget an offhand spoken “thank you”, but we usually bask in reading a well-written thank you note.

    I have made a concerted effort this year in both my personal and professional life to let friends, family and clients know that I am thinking of them and value them. This might be the most important part of my job.  Have you been on the giving or receiving end of surprises and vivid action?  Do you agree with this quote?

  • Operating Expense Desk Audit 101: How to Make Sure You Aren’t Overpaying

    Operating Expense Desk Audit 101: How to Make Sure You Aren’t Overpaying

    If your firm or company leases office space, the odds are good that you pay your landlord for actual annual increases in the cost of running the building.  Leases are either set up (1) to include a base amount of operating expenses in the rent (usually equal to the actual total costs in the first year of the lease term) and in subsequent years, the tenant reimburses the landlord for actual costs in excess of that base year amount (“full service”) or (2) to exclude these amounts from rent but allow for separate reimbursement from the tenant for all operating expenses incurred by landlord (“net”). 

    Whether net or full service, the landlord usually estimates operating expenses for the coming year and the tenant pays 1/12 of that estimated amount each month during the year.  After the year ends, the landlord reconciles what was actually spent to operate the building with what the tenant paid over the year.  The tenant then either pays any shortfall or is issued a credit for any overpayment against rents coming due.

    These reconciliation statements typically arrive at the end of the first quarter and often accounting departments pay them without review.  However, in my experience, it is worth taking a little time to do a quick audit of the statement.  Here is our approach:

    If your lease is full service, make sure that the base year reflected on the statement is accurate.

    Oftentimes a company will add expansion space over their lease term and that space will have a different base year than the original space. Or, if a lease is renewed and the tenant is given a new base year, occasionally the reconciliation reflects the original base year which is lower, resulting in more cost to the tenant.  It is worth confirming that all base years are correctly stated.

    Check “gross ups”.

    Most leases provide that tenants pay their proportionate share of operating expenses based on their share of the total building square footage.  So, if a tenant occupies 40,000 square feet in a 100,000 square foot building, the tenant pays 40% of the total operating expenses for the building.

    However, some expenses, like janitorial, are variable.  For instance, if 20,000 square feet are vacant in that same 100,000 square foot building, the landlord is not going to pay to have that space cleaned every day; the landlord is only going to pay to clean the 80,000 square feet of occupied space.  So, if the tenant pays its pro rata share (40%) of the actual janitorial costs incurred, that tenant is essentially paying for 32,000 square feet of cleaning which is less than  the appropriate cost.  As such, most leases contain clauses that allow the landlord to gross up variable costs to reflect a fully occupied building.

    In reviewing gross ups, make sure expenses being grossed up by the landlord are truly variable. Variable expenses are often specifically defined in the lease and usually include janitorial costs, management fees and utilities which understandably fluctuate with occupancy levels.  When we see landlords gross up taxes, we will question it because taxes do not get reassessed each year based on the occupancy rate in a building. Similarly, grounds maintenance should not get grossed up because grounds have to be maintained to the same standard regardless of occupancy levels.

    Compare last year’s itemized costs with this year’s.

    Have any expense categories increased by an inordinately large percentage compared to the other categories?  If there is not a simple explanation for it, i.e. utility rates increased, it is worth asking the property manager for more information.

    Are there any new categories of expenses reflected on the reconciliation that were not included in previous years?

    I had one client receive a reconciliation billing them for “lobby art”.  Their lease specifically provided that artwork was a landlord expense and could not be passed through to the tenant so the tenant was able to remove that $20,000 expense from their bill.

    Is the math correct?

    Sounds simple but I make mathematical errors regularly and property managers are fallible too.

    Check for capital expenditures.

    Most leases do not allow landlords to include capital expenditures in operating expenses unless they increase the operating efficiency of the building thereby decreasing operating expenses over the long term.  If your lease has language like this and there is a large capital cost included on the reconciliation, it is worth a friendly call to the property manager to get more information about the nature of the expense.

    As our team reviews reconciliations on behalf of our clients, we try to keep in mind the long-term nature of the landlord/tenant relationship; we want everyone to get along over the life of the lease.  As such, our approach is always collaborative in nature as we know most overcharges are inadvertent and usually quickly remedied by the property management team.  Is there a something I missed?  I would love to hear your comments! And, if you would like to download my list of operating expense exclusions, go to this page.

  • Are New Lobbies Enough? Making the Most of Older Buildings

    Are New Lobbies Enough? Making the Most of Older Buildings

    Today, most corporate office tenants seeking their initial spaces or relocating their offices lease space in newer buildings because newer buildings usually provide better environments for today’s businesses.  Not only are they fresher and more contemporary, they also usually feature the assets that are sought after by today’s businesses: environmentally friendly and efficient systems, technologically advanced infrastructure, efficiently laid out floor plates and professional management.

    If you currently own or are contemplating owning an older building, how do you make the most of it?  You have three choices (1) compete on price; (2) convert to hotel, residential or other use; or (3) invest in infrastructure.  Assuming choice 2 does not work for you for any number of reasons and further assuming you do not wish to race your competitors to the bottom on price, you need to consider investment and factor it into your pro forma.

    But where should you put those dollars?

    Vornado Property Trust in NYC recently improved 10 million square feet of older stock for future use.  According to Executive Vice President Glen Weiss, the improvements they made were “not just new lobbies”.  Rather, Vornado invested in significant infrastructure improvements to the building systems and worked with the city to close a street between two of its buildings to create an attractive outdoor gathering space.

    At Taconic Investment Partners, Co-CEO Paul Pariser said that they ask themselves of older buildings: “are the ceiling heights high enough? Are the view corridors long enough?” when determining where and how to invest in improvements.   If the ceilings are too low, some landlords have gone so far as to remove floors from the building.  Similarly, view corridors are extended by removing interior improvements to open up the space.

    Landlords also focus on adding amenities.  Empire State Realty Trust built a 15,000 square foot fitness center in one of their older Manhattan multi-tenant office buildings.

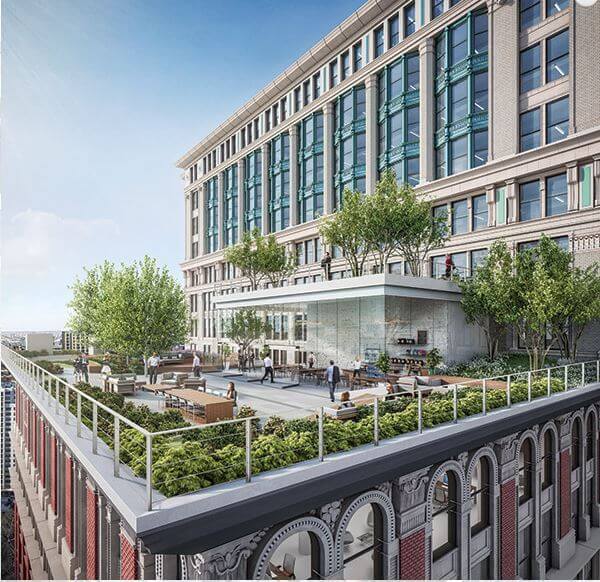
    When BuzzFeed recently negotiated to relocate to 225 and 233 Park Avenue, buildings originally built in 1909, the landlord agreed to build a glass staircase connecting the two buildings, a penthouse roof deck with a glass wall pavilion and a terrace overlooking the roof deck.  The landlord also agreed to install a destination dispatch elevator system and update the HVAC systems to better control the temperature in today’s more densely occupied offices.

    With infrastructure and amenity improvements, older stock can outshine newer buildings that lack the character and charm sought by today’s tenants and potentially out-earn the newer stock as well.  Tenants expect the systems to be modern and the lobbies to be inviting at whatever price point they consider.  The smart money complements those costs with well thought out strategic infrastructure enhancements.